Mortgages in Rossland
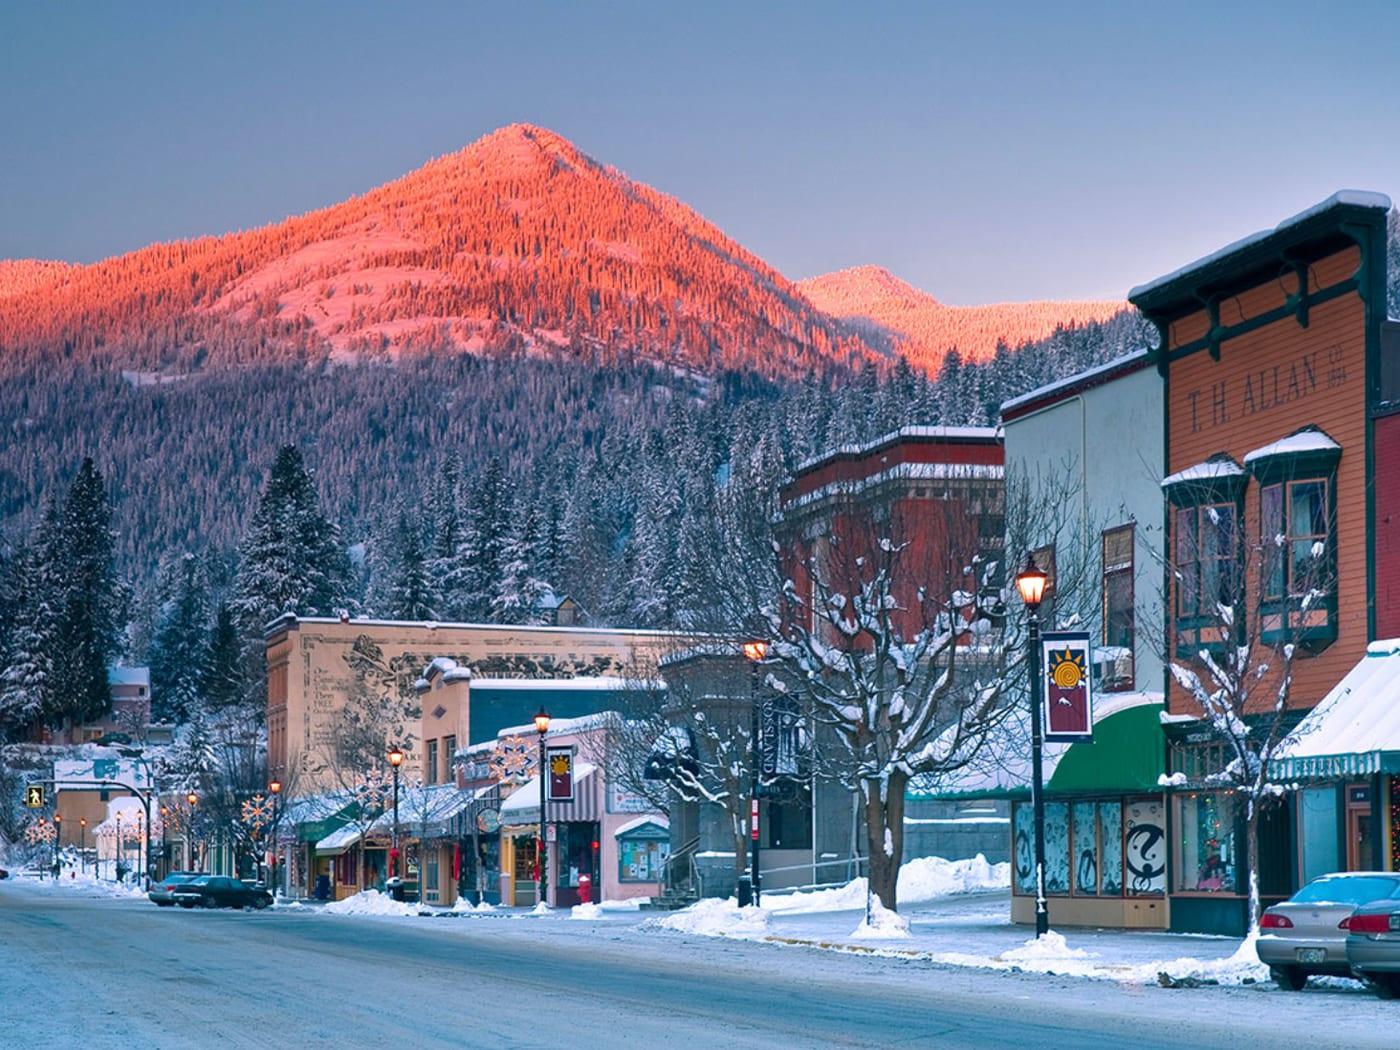
Rossland is a mountain town with Red Mountain Resort at its doorstep. It grew faster than any other town on this list between the 2016 and 2021 censuses.
Regional District of Kootenay Boundary
Home prices
What homes are valued at
City of Rossland
- Recent sale prices (single-family)
- Not published for Rossland
- The Association of Interior REALTORS publishes Kootenay-wide figures, not town-by-town ones. See their market statistics for the region. Checked Sep 30, 2026.
- Typical assessed value (single-family)
- $625,000
- BC Assessment's typical value for a single-family home. An assessed value, not a sale price. Period: valuation date July 1, 2025 (2026 assessment roll). Source: BC Assessment, 2026 assessments for the Southern Interior. Accessed Sep 30, 2026.
Figures last reviewed Sep 30, 2026.
By the numbers
2021 Census snapshot
Rossland (city) by the numbers
- Population, 2021
- 4,140
- Up 11% since 2016 (3,729) Released Feb 9, 2022.
- Households that own
- 80%
- 1,445 of 1,805 households Released Sep 21, 2022.
- Single-detached homes
- 77%
- 1,380 of 1,800 occupied homes Released Apr 27, 2022.
- Median owner costs
- $1,220/mo
- Mortgage, tax, utilities and fees, 2021. Includes owners with no mortgage. Released Sep 21, 2022.
- Median rent costs
- $1,200/mo
- Rent plus utilities, 2021. Released Sep 21, 2022.
- Median household income
- $96,000
- Before tax, for 2020. Released Jul 13, 2022.
- Median age
- 40.8
- 2021. Released Apr 27, 2022.
Source: Statistics Canada, 2021 Census Profile, Rossland. Accessed Sep 29, 2026. Census values are self-reported and from 2021, so they're a picture of the town, not current prices. Home prices are in the block above.
Living here
What's it like?
Up the hill from Trail, Rossland mixes full-time families with second-home owners and ski-season rentals.
That mix brings its own mortgage questions: suites, rental income and second properties.
What I'd watch for
Buying in Rossland: the details
Suites and rental income
For CMHC-insured mortgages, lenders can count up to 50% of the gross rent from the property you're buying. On a two-unit home you live in, up to 100% of the suite rent can count.
Short-term rentals
If you plan to rent nightly, check the City of Rossland's rules first. Lenders also look at short-term rental income differently from a long-term lease.
Second homes
Buying a place to use on weekends is a different file from a home you live in. Down payment and insurance rules change, so let's plan it early.
Questions
Asked about Rossland
Can I buy a ski-season place as a second home?
Often, yes. Down payment and qualifying work differently from a principal residence. Tell me how you'll use it and I'll show you the options.
I work remotely. Can I still qualify?
Usually, yes. Lenders look at the job, your history in it and how you're paid, not where your desk is. If you're salaried, a job letter and recent pay stubs usually cover it. An employer outside Canada can mean a few more questions.
Is buying a condo different from buying a house?
A little. The lender also reviews the strata - the depreciation report, recent minutes and the contingency reserve fund. Ask for those documents early so there are no surprises before your subjects come off.
Nearby
Other communities
Buying in Rossland? Let's talk.
Fifteen minutes on the phone usually clears it up. No pressure.